

Manager's Guide to Distribution Costs 2026
The 8th annual benchmark of commercial vehicle operating costs, overheads and market trends
Download
Foreword
I am very pleased to have been asked to write the foreword for this, the eight edition of the Freight Transport Association of Ireland (FTA Ireland) Manager’s Guide to Distribution Costs. Both I and my officials have found the report a useful and engaging reference point. This publication is a valuable resource for fleet operators across the sector, providing both a snapshot of the current environment, as well as demonstrating trends across the years which can help businesses to plan and grow.
Unsurprisingly, this year’s report has shown that a large majority of respondents are seeing increases in their total business and transport overhead costs. This year has been a particularly challenging economic environment, with global unrest leading to sustained and dramatic increases in the price of fuel. I note that 84.6 percent of respondents suggest that fuel price changes have had a ‘significant’ or ‘moderate’ impact on their operating costs. The Government recognises the uniquely difficult pressures that the Road Freight sector faces when fuel prices surge and has introduced general measures, such as reductions in the rate of excise and the NORA levy, as well as targeted sector specific measures such as the increase in the maximum rebate available to licensed operators under the Diesel Rebate Scheme from 7.5 cent to 12 cent.
In addition, in recognition of the essential role played by Ireland’s supply chains, the Government announced the operation of the Road Transporters Support Scheme (RTSS). The RTSS made funding of up to €120 million available to help road transport businesses offset escalating fuel costs. The scheme has a bigger budget and was available to a wider spectrum of operators than the Licensed haulage support schemes that were operated previously. A total of 4,406 applications were received in respect of 31,509 vehicles. 2,264 of applications were made by licensed road haulage operators, 456 of applications were made by licensed road passenger and 1,686 of applications were made by own-account operators.
I am heartened to see that, despite the complexities faced by the sector, respondents reported an average of 8.3 percent growth in revenue, achieving an average operating profit margin of 7.5 percent. While the margins remain narrow I think it’s important that we recognise that thanks to the expertise and professionalism I see daily within the sector, it remains solid and resilient.
This report identifies that filling driver vacancies persists as a concern for respondents. The number of days taken to fill a vacancy has continued to increase and it is an ongoing challenge to which this Government has brought a renewed focus. FTA Ireland are a valued partner in the effort to attract drivers from non-EEA countries to ease these recruitment challenges. The work done by FTA Ireland on documenting the process of recruitment from abroad to help relieve the shortage was an important and valuable step and my officials are engaging with other Departments to speed up that process.
Logistics and Supply Chain Skills Week 2027 will take place next year from Monday 19 to Saturday 24 April. I would like to invite all FTAI members to take an active role in the events taking place to ensure a successful and engaging week. The themes of the week will remain, ‘Global, Innovative and Resilient’. A particular highlight of the week for me is the LogisTYcs Expo for Transition Year students, Leaving Cert Applied students, their guidance counsellors, and teachers, which takes place next year on Thursday 22 April. The event is a wonderful opportunity to attract young people and get them excited about the careers available.
As we move closer to our 2030 climate targets, I am encouraged to see that over 90 percent of survey respondents now have sustainability policies in place. The biggest driver behind these efforts has been identified as the need to ‘meet expectations or requirements of customers, suppliers or service providers’.
This demonstrates how a strong commitment to reduce emissions and move towards a net zero future has become normalised and indeed is expected by customers.
I do however recognise that there is bias towards larger operators in the survey response and there is still a lot for the Government to do to assist, in particular, smaller operators in preparing for the transition. Once again, the expense of implementing green initiatives remains the biggest obstacle survey respondents perceive in their efforts to be more sustainable, with 80 percent identifying ‘Financial Cost’ as the biggest barrier.
This Government provides support to operator’s efforts to be more sustainable via the Zero Emission Heavy Duty Vehicle Purchase Grant Scheme. The scheme provides support for zero emission vehicles as well as for associated charging infrastructure. In addition, the SEAI administers the fleet assessment scheme which provides your organisation with an experienced assessor who will examine your current fleet and assist in identifying a pathway to fleet electrification. Electrification will play an important role in the transition to a zero emission sector, but I would also encourage operators to consider what role Hydrogen or Biomethane could play for their fleets.
This coming year will be an important milestone for my Department as we carry out the midpoint review of the Ireland’s Road Haulage Strategy 2022-2031. This process will include consultation with stakeholders to review existing actions, and we would welcome specific input from industry on how the Government can support decarbonisation not only through expanding subsides, but also through support for interim technologies which will reduce emissions in the short and medium term. I would like to encourage FTA Ireland members to engage with the process to best ensure the collaborative relationship we have developed continues to prosper.
Seán Canney T.D., Minister of State at the Department of Transport with special responsibility for International and Road Transport, Logistics, Rail and Ports
Introduction
FTA Ireland, in partnership with AIB, ECOfleet, Logistics Associate Apprenticeship and supported by specialist research agency Analytiqa, is pleased to present the eighth annual Manager’s Guide to Distribution Costs.
Since 2019, the report has provided an independent, practical evidence base for Ireland’s freight distribution, logistics and commercial fleet sectors. It tracks vehicle operating costs and the wider factors shaping performance and investment. That broader context is especially important in 2026. Freight and logistics businesses continue to face geopolitical instability, energy-market volatility and cost uncertainty. Recent pressures show how quickly international events affect domestic operations. Fuel-price movements feed directly into operating costs, working capital, customer pricing and confidence. For a sector that must keep vehicles moving daily, these pressures cannot be deferred. This year’s report explores how operators are responding. New questions cover business sentiment, fuel-price increases, pricing and surcharge adjustments, contractual fuel baselines and experience of the Road Transport Support Scheme. The research also considers impacts on capital expenditure, staffing, alternative-fuel priorities and customer delivery requirements. The findings show a resilient sector, but one that is becoming more selective about when and where it invests. Business overheads increased by an average of 7.3%, while transport overheads rose by 8.1%. Domestic haulage rates increased by only 2.7%. This continuing gap between cost growth and recoverable rates is placing pressure on margins and reinforces the need for fair, transparent and regularly reviewed commercial arrangements.
Energy costs remain central. More than eight in ten respondents said fuel-price changes had a significant or moderate impact on operating costs. Operators have responded through pricing changes, fuel surcharges and revised contractual baselines, although the effectiveness of these measures varies. One-third delayed asset purchases or changed capital expenditure plans directly in response to events in the Middle East. The proportion with no capital expenditure planned for the coming year also rose from 7.7% in 2025, to 21.4% in 2026. This matters beyond individual businesses. Delayed replacement may affect fleet age, maintenance, reliability, emissions and the introduction of newer technologies.
However, the picture is not entirely defensive. Among businesses continuing to invest, fleet replacement remains the principal priority, with technology, machinery and equipment also featuring strongly. Alternatively fuelled vehicles are now present in 60.0% of participating fleets, up from 52.9% in 2025, and user satisfaction has improved. Expectations for the overall scale of alternatively fuelled fleets by 2030 have nevertheless become more cautious, highlighting the difference between trialling vehicles and committing to wider fleet conversion. The report also broadens its assessment of business preparedness. It considers climate-related operational risks, future energy needs, cyber-risk training, driver welfare, employment-status arrangements, empty running and collaboration with customers. Fleet performance can no longer be assessed through vehicle costs alone. Energy capacity, workforce availability, digital resilience, infrastructure and management capability are increasingly important to competitiveness.
Recruitment remains a persistent challenge. More than three-quarters of respondents say recruitment difficulties affect day-to-day operations, while 71.4% report an impact on business growth. Driver vacancies take an average of 30.7 working days to fill, and fewer than one in five drivers in participating fleets are aged 40 or younger. These findings underline the importance of retention, training, apprenticeships and a sustainable talent pipeline. There are also clear efficiency opportunities. Telematics is used by every respondent, yet feedback identifies continued reliance on fragmented systems, spreadsheets, manual reporting and disconnected information. The priority is not simply to collect more data, but to convert existing information into better operational decisions, fuel management, compliance and utilisation of vehicles and people.
The Manager’s Guide to Distribution Costs helps operators benchmark performance, test assumptions and make informed decisions. It also helps stakeholders understand the costs and challenges of safe, compliant and sustainable freight operations. The findings reinforce the need for cost movements to be understood across the supply chain, procurement decisions to recognise operator viability, and public supports to be practical, accessible and capable of giving businesses confidence to invest.
Niall Cotton, CEO, FTA Ireland
Headline trends
In this section, we provide an overview of a commercial vehicle operator’s costs in Ireland, with a focus on business overheads, transport overheads, maintenance and fuel costs. Additionally, and new for this year, we track respondents’ sentiment on key current challenges facing the sector.
Business overhead costs
In 2026, none of our respondents have reported decreases in their total business overhead costs in the last year. Almost nine-out-of-ten companies that took part in our research (85.7%) have reported an increase in business overheads in the last year, with 14.2% experiencing an increase of more than 10.0%. The average increase in business overhead costs reached 7.3% this year, down marginally from 7.6% in 2025.
Annual business overheads were defined as those involved in running the business, distinct from the costs involved in running the transport operation itself, and included, for example, the cost of renting office space, salaries of administration, sales, marketing and accounting personnel, and utilities bills such as water, electricity and gas etc.
Historically, across our series of reports, the cost increases experienced by our respondents compare unfavourably with the published rate of inflation in Ireland (Consumer Price Index). The Consumer Price Index (CPI) rose by 2.7% between January 2025 and January 2026, down from an annual increase of 2.8% in the 12 months to December 2025. Prices on average, as measured by the CPI, were 3.4% higher in July 2026 compared with July 2025. More details on inflation rates can be viewed in the market data appendix at the end of the report.
Transport overhead costs
Similar to our research across the 2022-2025 period, none of the companies participating in 2026 experienced a decline in transport overhead costs in the last year. Over three-quarters of companies (77.8%) reported that their transport costs increased by more than 5.0% and one-third (33.4%) suggested that the increase was 10.0% or more. On average, transport overhead costs were reported to have increased by 8.1% in the last year, down from 9.1% in the prior year period.
Transport overheads are those associated with the day-to-day running of the transport operation and include, for example, the transport manager’s salary, despatch office running costs, tachograph analysis costs, maintenance of fuel storage tanks etc.
To put these cost increases in context, data included in the market data appendix at the end of this report identifies that laden transport journeys across Ireland increased by 10.9% in 2025, as volumes (tonnes carried) increased by 2.4%.
Revenue, profit and haulage rates
The increase in business and transport overhead costs should be placed in context with any increase in prices (rates) that service providers are able to achieve with customers and subsequent changes in revenue and profits. Whilst haulage rates are increasing year-on-year for many fleet operators, but not all, at 2.7%, the average percentage change in domestic haulage rates achieved by our respondents remains significantly below the reported increases in transport operating costs.
For the third time in our series of reports, we asked respondents to provide details of revenue growth and profit margin for their most recent financial accounting period. Whilst not indicative of industry-wide averages, it does help place our analysis of costs in context.
Our respondents reported 8.3% growth in revenue, on average, down marginally from 8.7% last year, achieving an average operating profit margin of 7.5%, up from 6.8%.
Attempting to illustrate the competitive nature of road transport in Ireland, this year, for the first time in our series of reports, respondents disclosed that, on average, 2.6% of work (revenues) have been lost in the last year due to rate / price undercutting by competitors. Respondents suggested that 1.4% of work (revenues) have been lost due to “below cost” undercutting rates.
72.7% of our respondents consider themselves to be ‘buyers’ of haulage services, including companies that sub-contract work. Just over one-third (36.4%) aim to boost the efficiency of their operations by making use of return load rates.
More than nine-out-of-ten of our respondents (91.7%) classify themselves as providers of haulage services, including those that work as sub-contractors and / or own-account operators that may undertake some work for third parties. Of these companies, the average number of customers per company is 65.1, whilst just under one-half (45.5%) offer return load rates to customers.
18.2% of overall respondents that are providers of haulage services undertake cabotage, whilst 25.0% of our respondents identifying themselves as road hauliers are undertaking cabotage.
This year, for the first time in our series of reports, we investigated ‘empty running’ by Ireland’s fleet operators. Respondents disclosed the share of kilometres travelled by their fleet that they would define as ‘empty runs’. On average, they suggested that 12.5% of their distances would be defined as such. This figure is somewhat below other available metrics, so should be treated with caution, and is a data point to keep an eye on in future editions.
On a positive note, 60.0% of our respondents suggested that they are collaborating with customers (and others) to reduce empty running of their fleets.
The current climate
Ireland’s fleet operators are not immune to global pressures witnessed over the past 6–9 months, from fuel price spikes to supply chain instability. New to our research this year, we asked our respondents the following ‘series of sentiment-based questions’ to gauge the sector’s opinions and reaction to market dynamics beyond their control.
1. The impact of fuel price changes on operating costs
38.4% of respondents suggest that fuel price changes have had a ‘significant’ impact on their operating costs, with a further 46.2% reporting a ‘moderate’ impact.
2. Adjusting pricing or fuel surcharge as a result of changes in fuel prices
15.4% of respondents have changed both pricing and surcharge in response to increasing fuel prices in 2026. 30.0% of respondents have altered only their pricing, with 53.8% electing to alter only their fuel surcharges.
3. Use and management of fuel baselines in contracts
Only 7.7% of respondents do not use a fuel baseline in contracts. 61.5% of respondents regularly review their baselines whilst a further 23.1% will periodically review them.
4. Company approaches to the Road Transport Support Scheme (RTSS)
61.5% of our respondents have applied for and received support under the RTSS. Almost one-quarter of respondents were ‘unsure’ of their approach, attributing this largely to uncertainty, having applied but not yet receiving feedback or pay-outs.
5. In direct response to the crisis in the Middle East…
Lastly, we asked our respondents about the impact of events in the Middle East on their businesses. One-third of respondents (33.0%) have delayed purchasing assets or changed Cap-ex plans as a direct result. One-quarter suggest that investing in alternative fuels or electric vehicles is now a higher priority, whilst a similar share noted that customers (delivery locations) have widened and/or relaxed delivery windows to reduce return journeys in efforts to lower fuel consumption. 15.4% of companies suggested that their staff numbers have fallen as direct consequence of events in the Middle East.
Maintenance costs
The average increase in maintenance costs amongst our respondents increased to 5.6% this year, down from 11.1% last year. 14.2% of respondents reported lower costs, whilst 42.9% of companies reported an increase in maintenance costs of between 1.0%-5.0%. The same share of respondents (42.9%) noted an increase of more than 5.0%, though no companies have seen their maintenance costs rise by more than 10.0% in the last year (compared to 57.1% last year).
For the first time in our report series, this year we sought to identify maintenance cost comparisons for vehicles by fuel type. Whilst, anecdotally, we are able to suggest that monthly maintenance costs for the largest trucks running diesel may be ~70.0% more than their electric counterparts, and those of similar sized BioCNG/CNG trucks are more than diesel, this is not based on a sample size large enough to be definitive. Therefore, we would advise caution when considering this data. It is, however, a data point that we will be revisiting in subsequent editions.
Fuel costs
77.8% of our respondents reported an increase in commercial vehicle fleet fuel costs in the last year, with average annual growth amongst our respondents rising to 5.9%, from 5.2% last year. 22.2% reported a more than 10.0% increase in their fuel costs, up from 18.1% last year. At €0.48, average fuel costs per kilometre across commercial vehicle fleet operations increased from €0.45 last year in line with the €0.49 cost per kilometre recorded in 2024.
These average costs continue to be significantly higher when compared to the consistent findings recorded across our first three reports (2019-2021).
For further context, changes in retail diesel prices are provided in the market data appendix at the end of this report.
Breakdown of costs by vehicle type
Our analysis segments the annual operating costs by types of commercial vehicle, identifying the share of costs allocated to drivers, fuel and insurance. The ‘other’ category covers additional vehicle (and trailer were relevant) costs associated, including maintenance and deprecation.
For rigid vehicles, we see that driver costs account for 43.1% of a vehicle’s operating costs, with fuel making up a further 32.7% of the total, with these figures combining to represent three-quarters (75.8%) of the vehicle’s operating costs.
For 46 Tonnes articulated vehicles, the share of operating costs accounted for by drivers is 32.6%, whilst fuel accounts for a 46.3% share.
__________________________________________________________________________________________________________________
Finance
In this section of the Manager’s Guide to Distribution Costs we analyse key financial metrics of fleet operations, taking an in-depth look at insurance, cashflow and future plans for capital expenditure, whilst seeking to understand priorities for the leadership and governance of businesses and their management planning processes.
We have expanded our focus on sustainability, to understand not only fleet operators’ motivations and credentials, but also the challenges they face in being ‘green’. Our research identifies the focus of fleet operators’ investments, and if this delivers a return to their businesses, whilst also asking if companies are employing staff to focus solely on ESG.
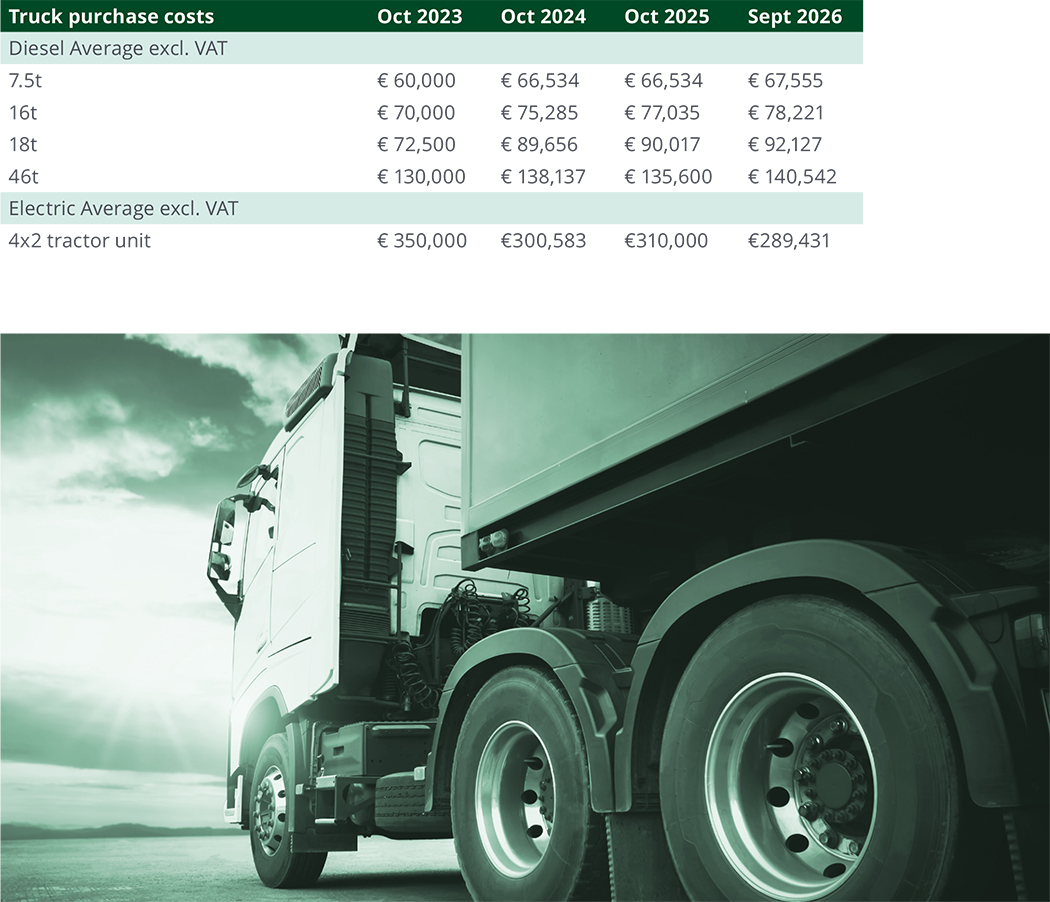
Truck purchase and leasing costs
Our research once again asked respondents how much money they put aside each month to save towards the purchase of new vehicles for their fleets. Across a diverse range of fleet operators, these amounts will vary enormously by company, not least due to the size of fleet, the type of vehicles operated and a company’s propensity to purchase and / or lease vehicles. Given all of these factors, the average level of monthly savings amongst our respondents was €7,000, some way below the €9,009 average recorded over the five years where we have tracked this metric.
Similar to the investigation of savings for new vehicle purchases above, we also asked respondents to disclose the size of the monthly repayments they make to external finance providers for the lease of their commercial vehicle fleet. Once again, these amounts will vary depending on the size and make-up of a company’s fleet, but respondents revealed that, on average, they are paying €62,686 per month to external finance providers, which is almost 10.0% above average for the five years where we have tracked this metric.
Type of motor insurance
Almost nine-out-of-ten (89.9%) of commercial vehicle fleet operators rely solely on traditional forms of insurance to safeguard their assets. 6.7% of respondents use a combination of self-insurance and traditional fleet insurance.
Timing of insurance renewals
Just over one-half (53.9%) commercial vehicle fleet operators insure their vehicles in the first half of a calendar year, matching our research in the last two years, with 30.8% doing so in the Q3 period.
Motor insurance premiums
Commercial vehicle fleet operators were asked to provide details of their current annual insurance premium, or, if they self-insure, the amount that is set aside for their commercial vehicle fleet. Note that whilst we see costs for heavier trucks being more expensive, costs by vehicle type display fluctuations from year-to-year, which are explained by a different mix of vehicle types and business uses amongst respondents.
Over nine-in-ten respondents (91.0%) reported an increase in their annual insurance premium at the time of their most recent renewal, with 45.5% indicating a rise in premiums of 5.0% or more in the last year.
Some fleet operators, but not all, are taking direct action to reduce their motor insurance premiums. One-third of respondents (down from 46.7% last year) stated their drivers have undertaken safety driving courses in the last year in an effort to lower insurance premiums. Participation in structured safety programmes such as FTA Ireland’s TruckSafe can also cut claims costs and reduce insurance premiums by demonstrating a proactive safety and compliance culture.
Financial and strategic performance
Reflecting the methodology applied across our previous editions, this report again evaluates companies’ cashflow and working capital practices to identify structural patterns and emerging shifts.
This year, we find that 69.2% of respondents believe they fully optimise their working capital, up from 61.5% who gave this reply last year. The remaining respondents (30.8%) admit they only partly achieve this, suggesting that there is still room for improvement across the industry.
Fleet operators face numerous cashflow challenges, including managing delayed payments from customers. From 2023-2025 this issue dominated respondent’s finance departments. This year, we find it is a key concern for one-third of our respondents, whilst the same share (up from 23.1% last year) believe they do not face any significant cashflow challenges. 16.8% of respondents indicate that they face multiple cashflow challenges, including bad debts, creditor/ debtor terms and delayed payments.
In line with our previous research, the ‘turn of the year’ period, from December, through January and into February continues to be the most crucial time of the year for fleet operators managing their cashflow. Two-thirds of companies report this as their most challenging time of the year, with February (33.4%) being the single most challenging month.
The late Summer / early Autumn period, from August to September is also identified, once again, as a difficult period to navigate.
Just under one-quarter of companies (23.1%) are aware that their company makes use of invoice discounting solutions to assist in cashflow management of their business. Each year, respondents to our research are drawn from a variety of job functions, from business owners, to finance professionals, operational and transport staff. Whilst 69.2% of respondents state that their company does not make use of invoice discounting solutions, 7.7% do not know if their company use them.
Recognising the importance of good recruitment
This year’s research confirms that fleet operators undertake staff scenario planning, with all of our respondents indicating this to be the case. One-in-five companies assess staff scenario planning weekly, 46.7% do so monthly and a further one-third do this quarterly.
In addition to staff scenario planning, our research also identified that over three-quarters of respondents (78.6%) undertake succession planning to support the future growth and strategic direction of their businesses.
Recruitment plays an increasingly significant role in business success. 71.4% of respondents (70.6% in 2025) believe that their company’s ability to recruit is impacting the growth of their business, whilst almost over three-quarters (76.9%, up from 64.3% last year) suggest that it is also impacting their day-to-day business operations.
Leadership and governance
Once again, we asked respondents to identify their biggest priority in the year ahead regarding the leadership and governance of their companies. 36.4% of respondents suggested that the provision of training to support business leadership is a priority (down from 45.4% last year), with the same share identifying that resolving skills gaps amongst senior leaders is their biggest priority.
Respondents were once again asked to pinpoint their top leadership and governance priority for the year ahead, and the picture has shifted. Just over one-third (36.4%) now place leadership focused training at the top of their agenda, a drop from last year’s 45.4%. At the same time, an identical share highlights closing skills gaps among senior leaders as their most urgent concern, underscoring growing pressure on business leaders’ performance. The need to overcome challenges in succession planning is an increasing priority for respondents, with 27.2% highlighting this as their key challenge, up from 18.2% last year.
Investing in growth
21.4% of respondents state that they have no plans for capital expenditure in the coming year, a significant increase from the 7.7% that aligned with this sentiment in 2025. This suggests that the challenging market dynamics of the first half of 2026 have promoted changes in strategy amongst fleet operators.
Of those respondents that are undertaking capital expenditure, over one-quarter (27.3%) report that they will manage this from their existing reserves, whilst 36.3% will use a combination of reserves and debt. 27.3% of respondents (up from 16.6% last year) will utilise asset lender debt. On average, the levels of capital expenditure are forecast to be 17.8% higher in the year ahead.
Capital expenditure is likely to be fairly well distributed across a calendar year, though over one-quarter of respondents (27.2%) suggested that July would be the peak month for their spending.
For those companies that are undertaking investment, the main priority in 2026/2027 is fleet, with all of our respondents set to invest in this area. 55.6% of companies participating in our research state that they will be investing in environmental projects, a significant drop from the 80.0% level of 2025.
Three-quarters of respondents will invest in machinery and equipment and 69.2% are set to invest in technology. Similar to last year, around one-half (46.2%) are expecting to invest in the retro-fit, upgrade and refurbishment of existing warehouses or storage facilities while one-third will be investing in new storage facilities.
Sustainable supply chains
It is pleasing to see that 93.3% of respondents say their companies have sustainability policies in place, up from 84.2% last year. This should be placed in the context of the profile of our research respondents, which is weighted towards larger fleet operators.
The main motivation in a company’s efforts to be more sustainable continues to be the need to meet expectations or requirements of customers, suppliers or service providers. This is followed, this year, by a desire to make a positive social and environmental impact.
85.8% of respondents, up from 70.6% last year, state that their company has sustainability credentials (that is certifications, confirming to standards etc).
The financial cost of implementing sustainability initiatives is the biggest barrier companies face in their efforts to be ‘green’, highlighted by 80.0% of respondents. Just under two-thirds (64.3%, down from 73.3% in 2025), state that sustainability initiatives (policies and/or credentials) have assisted in tendering for more work and/or have contributed to contract wins. 35.7% of respondents, down from 42.9%, are aware that their company has already received a grant towards the financial cost of its sustainability initiatives.
Preparing for future change
For the year ahead, investment in EV chargers or other alternative fuel infrastructure, social initiatives and ESG skills and training are high on the agenda for our respondents.
53.8% of our respondents state that their company already has personnel employed solely to focus on ESG and 30.8% expect to recruit people to such roles in the year ahead.
New to our research this year, we asked respondents if their company has assessed climate-related risks to their operations (e.g. flooding, extreme weather, site resilience). One-third state that their company has undertaken partial assessments, whilst a further 8.3% identified that full assessments have been completed. A similar share suggest that assessments have been planned but not yet completed.
Whilst only 8.3% of respondents state that no work has been carried out in this area, almost one-half (41.8%) were unaware if assessments had been undertaken.
For the first time in 2026 we also asked of fleet operators have assessed their future energy needs (e.g. electricity demand, grid capacity, EV transition). Over one-quarter (28.6%) suggested that an assessment has been completed, and actions taken (e.g. ESB application, energy audit) with a further 7.1% stating that an assessment has been completed but no action has yet been taken. One-in-five companies (21.4%) identified that an assessment in progress, whilst 42.9% were unable to confirm whether assessments have been undertaken.
Truck operating analysis
Please download report for data and commentary
Comparative analysis by vehicle type
Please download report for data and commentary
Tyre landscape overview
Please download report for data and commentary
__________________________________________________________________________________________________________________
__________________________________________________________________________________________________________________
Procurement, energy & eco training
Progress, but at different speeds
The 2026 survey shows continued progress in fleet renewal, alternative fuel adoption, data use and driver training. Average vehicle age fell across vans, rigid and articulated vehicles; annual utilisation was broadly similar to 2025.
The share of companies running at least some alternatively fuelled vehicles rose from 52.9% to 60.0%, satisfaction among users from 4.8 to 7.5 out of 10, and reported savings from alternative fuels averaged 5.7%, against 3.0% in 2025.
Expectations are more cautious: 57.1% of operators not yet using alternatively fuelled vehicles have no confirmed investment timescale. On the fleet data supplied, respondents expect their alternatively fuelled fleets to be 44.3% larger by end-2030 — a different measure from 2025, so not a direct year-on-year comparison.
Infrastructure remains a constraint
Infrastructure concerns eased but remain significant: 81.8% of respondents cited uncertainty over the availability and accessibility of high-speed charging for heavy-duty vehicles, 83.3% poor visibility of hydrogen refuelling locations, and 54.5% limited access to, or information about, the electricity grid.
Vehicle capability, purchase cost, charging infrastructure, battery life and residual values also remain concerns, so transition requires early assessment of routes, duty cycles, depot energy needs and total cost of ownership.
Making better use of fleet data
All respondents now use telematics and vehicle tracking. More than nine in ten report fleet performance regularly to senior management, 91.7% use fuel data for staff and driver training, and fleet data also informs procurement and sustainability reporting.
But fragmented systems, spreadsheets, manual inputs and integration difficulties persist: some fleets collect substantial data without a consolidated view of utilisation, route efficiency, fuel use and driver performance. Use of artificial intelligence in fleet optimisation was broadly unchanged at 23.1%.
EcoDriving delivers measurable savings
EcoDriving is among the most practical ways to improve efficiency without replacing vehicles or waiting for new infrastructure. An average of 74.4% of commercial vehicle drivers have received EcoDriving or similar fuel-efficiency training — up from 68.0% in 2025 and the highest in six years — and operators reported average savings of EUR 39,625 over the previous 12 months.
It works best with clear performance measures, constructive coaching and refresher sessions. Incentives are spreading: 38.5% of operators now offer financial rewards, against 18.8% in 2025, averaging €488 per driver a year. Comparisons must account for vehicle specification, payload, route conditions, congestion and operational requirements; drivers engage more when measures are transparent, achievable and recognise improvement.
Maintaining momentum
Change is gradual rather than uniform. The immediate opportunity is to use existing information more systematically, set reliable baselines and focus on a small number of meaningful measures. Alternative fuels and zero-emission vehicles will be central to longer-term decarbonisation, but uptake depends on suitable vehicles, infrastructure and a viable business case.
"Better use of data and sustained EcoDriving improvement can reduce fuel use, operating costs and emissions now, while preparing fleets for a more diverse, technology-led future."
Conor Molloy, MSc (Energy), CEM-I, CMVP, Registered Energy Auditor, ECOfleet
Vehicle procurement
Over one-half (53.8%) of commercial vehicle operators in Ireland pass responsibility for the acquisition of vehicles to a leasing company, whilst 30.8% issue RFQs, or tenders, based on price. The remaining 15.4% of operators are issuing RFQs, or tenders, based on the anticipated life cycle costs of their vehicles.
For the second time in our report series, this year we once again asked respondents to rate the importance of vehicle price in their truck purchasing decision making. We asked respondents to provide a score from 0 to 10, where 0 indicates where prices have no bearing on investment decisions and a score of 10 reflects that prices are the most important factor in investment decisions.
The average score awarded by respondents was 7.4, down just marginally from 7.7 in 2025. It was interesting to note that 85.8% of respondents provided a score of six or greater (up slightly from 83.3% last year).
Alternative fuels
The uptake of alternatively fuelled vehicles continues to increase and our research confirms fleet operators’ significant interest in decarbonising their fleets moving forwards.
Once again, we asked respondents the extent to which they had already embraced the use of alternatively fuelled vehicles in their commercial vehicle fleets. This year 60.0% of respondents (up from 52.9% last year) claimed that they were operating alternatively fuelled vehicles, a significant rise from 33.4% that reported this in 2024.
Whilst larger fleet operators, in particular, may have either already undertaken their initial research and / or actively already invested alternatively fuelled vehicles, one-third of our respondents indicated that they are currently exploring battery / electric vehicles for their fleet operations. One-fifth of respondents are exploring the use of hybrid electric vehicle options whilst 33.3% are investigating bioCNG/CNG vehicle types.
We also asked respondents that are not currently operating alternatively fuelled vehicles, when they expect to do so.
Our research this indicates greater uncertainty over timelines amongst our respondents, with 57.1% (up from 37.5% last year) stating that they have no confirmed timescales to invest. 14.3% suggest that investment in alternatively fuelled vehicles is imminent in the short term, with a similar share stating that it would be in the next two years (2027-2028) or alternatively, the 2029-2030 period.
Based on the fleet operating data provided in the research process, this would indicate that, in comparison to the start of 2026, our respondent’s alternatively fuelled vehicle fleets will be 12.1% larger by the end of the year, 27.0% larger by the end of 2028 and 44.3% larger by the end of 2030.
Further data on the use of alternative fuelled vehicles in Ireland is provided in the market data appendix.
In response to the increasing use of alternatively fuelled vehicles, we asked respondents to provide a high-level ‘satisfaction score’ to describe their experiences. Rating scores from 0 - 10, where 0 reflects the lowest and 10 the highest levels of satisfaction, or respondents delivered a score of 7.5 on average, up significantly from 4.8 last year, with all respondents providing a score of six or above.
To understand fleet operators concerns about transitioning to alternatively fuelled vehicles, over one-half (54.5%, down from 69.2% last year) stated that they have limited access to, or insufficient information about, the electricity grid. 81.8% (down from 92.3% last year) suggested that they have uncertainty about the availability and accessibility of high-speed chargers for heavy-duty vehicles, whilst 83.3% (down from 90.9%) attributed the delays in their commitment to a lack of visibility regarding the locations of refuelling stations.
Other notable concerns, or barriers, to making investments continue to include the operational functionality of vehicles, the costs involved, not only of vehicles but also that of charging infrastructure, dependable assurances about battery life, and also the resale value of trucks.
Reporting and monitoring fuel consumption
When asked to identify the cost savings that our fleet operator respondents are making from the use of alternative-fuelled vehicles. For those of our respondents using alternative energies, across all fuel types, the average cost saving was 5.7% this year, up significantly from 3.0% last year – and the biggest cost saving metric we have recorded in six years, likely reflecting the diesel price hikes witnessed this year.
In their attempts to save money on fuel one-half of respondents (50.0%) have fuel escalators and/or premium pricing for reduced CO2 / electric / HVO fuelled journeys, as part of their operations and commercial relationships).
These are transparent methods of dealing with fluctuating fuel prices, as a surcharge both increases and decreases in line with the actual fuel prices paid. 75.0% of our respondents that are using fuel escalators stated that they review these on a monthly basis, whilst over one-half (54.5%) of all respondents stated that they are using the Diesel Rebate Scheme.
63.6% of our research respondents indicate that fuel cards are used to monitor fuel consumption for commercial vehicle fleets. 27.3% of companies use a combination of approaches to report fuel use, across fuel cards and telematics systems, whilst 9.1% use other, bespoke systems, largely defined as ‘manual’ reporting, based upon driver feedback, logging / data recording and also charge point monitoring of EVs.
The challenges that research respondents see in collecting, reporting and analysing fuel data are numerous, and continue to remain consistent with previous feedback. Challenges noted by respondents include:
- Technological challenges, including lack of 4G network signal and impact of power outages
- Achieving a consolidated view of vehicle utilisation, driver performance, and route efficiency in real time
- Monitoring compliance is reactive rather than proactive due to limited data visibility and alert systems
- Limited intelligence where routing is based on static schedules, not real-time traffic or load balancing
- Data accuracy and integration across platforms
- Efficient utilisation of resources. Reporting processes are time-consuming and reliant on manual inputs
- Ad hoc nature of order patterns from customers
- Fleet managers that still use spreadsheets and periodic downloads instead of live dashboards
How is this fuel data used?
Maintaining the exceptionally high responses that we have recorded over the last three years, once again more than nine-out-of-ten companies use fleet data to report performance to senior management on a regular (weekly/monthly basis), whilst an eight year high of 91.7% of respondents also use the data to assist in the training of staff and drivers. 84.6% of fleet operators use fleet data in the procurement of new vehicles and a similar share use such the data to promote their company’s ‘green’ credentials and sustainability efforts.
Transport management and planning
This year, and for the second successive year in our report series, all of our research respondents stated that their companies use vehicle telematics or tracking to plan and control their commercial vehicle fleets. Whilst this continues to reflect a greater uptake of telematics and tracking across the industry, it is also remembered that our report’s respondents are weighted towards the country’s larger fleet operators. Building on last year’s introduction, we again asked if companies are using Artificial Intelligence (AI) tools in their fleet optimisation. Just under one-quarter (23.1%) of respondents stated that they are utilising AI for this purpose (in line with the 23.5% last year).
Company transport management and planning costs
Average annual costs related to transport management were, for the first time in our report series, in excess of €45,000 per company, a big jump from 2025. This equates to an average of €764 per vehicle across all vehicle categories, with the lower number this year reflecting the higher average fleet sizes of our respondents. Transport management and planning costs are defined as the total financial cost for tools used by operators to plan, control and monitor their commercial vehicle fleet. This includes costs of initial system purchase and / or ongoing fees. If an in-house developed system is used, we identified the financial costs allocated to the system’s upkeep, maintenance and development
Action and incentives to save fuel
Amongst the companies taking part in our research this year, on average, 74.4% of commercial vehicle drivers have received ‘Ecodrive’ training, or similar – the highest share in the six years that we have tracked this metric. Across the six-year period we see an average take up of such training at 65.8%.
Likely encouraged by the work undertaken by FTA Ireland, almost three-quarters of our respondents (72.7%) are aware of and/or have used standard/certified schemes for driver ‘Ecodrive’ training. Whilst anecdotal insight suggests low take up of the standard, the significantly higher figure generated by our research is likely attributable to the larger share of FTA Ireland members participating, who will be more aware of the work that FTA Ireland undertake in this area. Respondents suggested that their average cost savings from use of ‘Ecodrive’. or similar, training has been €39,625 over the last 12 months. 53.8% of commercial vehicle fleet operators do not offer their staff incentives to save fuel.
Amongst those operators that do offer fuel saving incentives, there is a mix of approaches on how best to achieve this across both non-monetary and purely financial-based incentives. Amongst those operators offering financial incentives, on average €488 is spent per year, per driver, to encourage more efficient use of fuel. Recognising the increasing importance of fuel saving efforts, companies are willing to spend more to encourage their drivers to act.
Now in it's 8th edition
Contact us to access copies from previous years

Extracts from the report...
About FTA Ireland
The Freight Transport Association Ireland CLG is a not-for-profit membership trade association for the Irish freight and logistics industry. Wholly owned and governed by members the association acts solely in advancing their best interests covering all aspects of private and public freight transport, passenger transport and logistics and supply chain sectors, including road, rail, sea and air.
About Allied Irish Banks (AIB)
Allied Irish Banks (AIB) is a major financial services group operating predominantly in the Republic of Ireland and the UK, offering a comprehensive range of services to retail, business, and corporate customers. It is one of Ireland's largest banks, with a history dating back to 1825, and its operations include commercial banking, financing, and investment.
Get in touch